What it does
Underwriting of a property: income, debt, returns, scenarios: a deep analysis of one asset with every figure pinned to its source. It is the single most-requested job we have: it appears in 28.6% of working conversations, whether or not people reach it through this named product.
When to use it
Use it on one asset when you have its documents: the T-12, the rent roll, the OM. Accuracy comes from your files: the product reads them, reconciles them against each other, and underwrites from your numbers. One address per run; for a list, use BOV at Scale.
Do not ask it for a view on the market's future in general (that is Assumptions) or for a licensed appraisal.
How to use it
- Open Underwriting under Analysis in the left list. The first tab is New underwriting, and it asks you to Attach the property documents.
- Drop the documents (PDF, XLSX, CSV, DOC or a ZIP folder): the T-12, the rent roll, the offering memorandum, and anything else you hold (operating statement, debt terms, capex budget). Every file is classified and read on arrival.
- Check the two rows under the documents: Playbook (your own underwriting standards ride with this run) and Assumptions (hold period, exit cap, rent growth, vacancy, OpEx, management fee).
- Under Anything to add before it runs?, state what you want tested (the debt you have in mind, the scenario you doubt) and press Start.
What you get back
- An IC memo (PDF and DOCX): start here;
- a Presentation (PPTX and PDF);
- an Excel model (XLSX), built on request;
- for analysts, the full report and every stated figure, in the room with the run's files.
Figures the documents state always win over an assumption. Every underwriting you run is on the Underwritings tab.
Time and cost
Median cost is under a credit, but the 90th percentile reaches 14; the spread is wide because the work is.
Your assumptions ride with every underwriting
This is the single thing that most changes what comes back, and almost nobody uses it: the Assumptions tab holds your house standards (hold period, exit cap rate, rent growth, vacancy and credit loss, OpEx inflation, management fee, and about fourteen more) and the engine appends them to every underwriting you run, not just the next one.
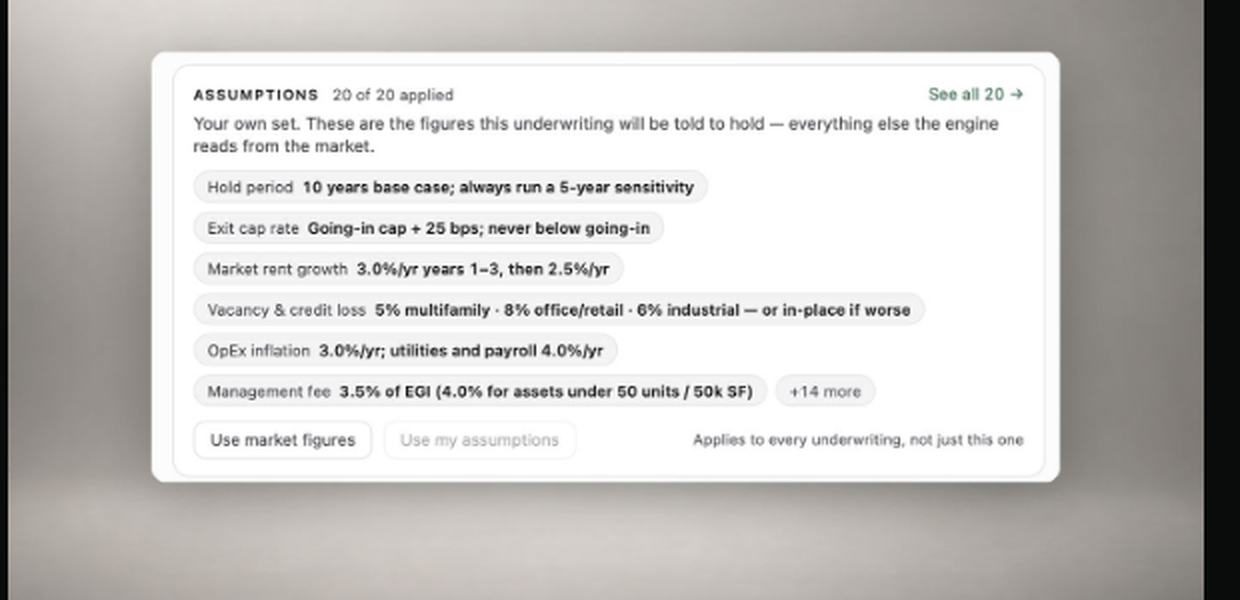
Two things worth knowing before you press Start:
- The set is per person, not per run. Changing a line here changes every future underwriting. There is no per-run override, and the interface says so rather than offering a switch that quietly rewrites the rest.
- "Market figures" is a real branch, not a label. Switch every line off and the engine underwrites from its own market reads instead of your standards.
Four people have ever set their own. Everyone else is running on the shipped defaults, which are reasonable, and are not yours. If your firm has a house view on exit cap or vacancy, twenty minutes in that tab is worth more than any other twenty minutes you will spend here.
Do
- Send the T-12 and the rent roll. Everything else on this page is secondary to that.
- Set your assumptions once, then check the Assumptions row before you start: it shows which ones are about to be applied and whether they are yours or the defaults.
- State the debt assumptions you want tested. Leverage, rate, term, amortisation: if you do not state them, they are inferred, and an inferred capital stack is the fastest way to a number you cannot defend.
Do not
- Do not count on a workbook. About half of finished Underwriting runs come back with one (31 of 62 in the 30 days to 12 October 2026); the rest do not. If you need a model you can open, run Excel, the product built to return one.
- Do not assume local tax or tenure rules are applied. They are not, in any country; state the ones that matter in the brief. See Coverage and data.
- Do not read a thin income section as a weak asset. It usually means we were underwriting from county data because no documents arrived.
- Do not assume the figures were your house standards. Unless you have set them, they are the shipped defaults, and four people in total have set their own. Check the row rather than the output.